Credit Risk And Payment Default Escalation for Australian Businesses
Defining a Risk Visibility Framework for Accounts Receivable
In an environment where credit risk and payment default escalation are increasingly pressing concerns, finance managers and business owners must develop clear visibility over their accounts receivable. Early detection and ongoing monitoring of risk indicators enable timely prioritisation decisions that help safeguard cash flow without premature escalation.
Key metrics to monitor for early detection of payment default escalation
Effective risk visibility begins with selecting relevant metrics that signal deteriorating debtor health or payment behaviour. Critical indicators include:
- Days sales outstanding (DSO): Rising DSO can reflect slowing payments and emerging cash flow pressure.
- Invoice ageing distribution: Concentrations of invoices beyond standard payment terms highlight potential default clusters.
- Customer payment frequency and history: Changes in payment punctuality or partial payments suggest increasing risk.
- Credit utilisation and exposure: Tracking the total outstanding amount per customer against credit limits reveals overexposure.
Together, these metrics provide a quantitative foundation to detect trends that may warrant closer review or intervention.
Tools and dashboards for real-time credit risk tracking
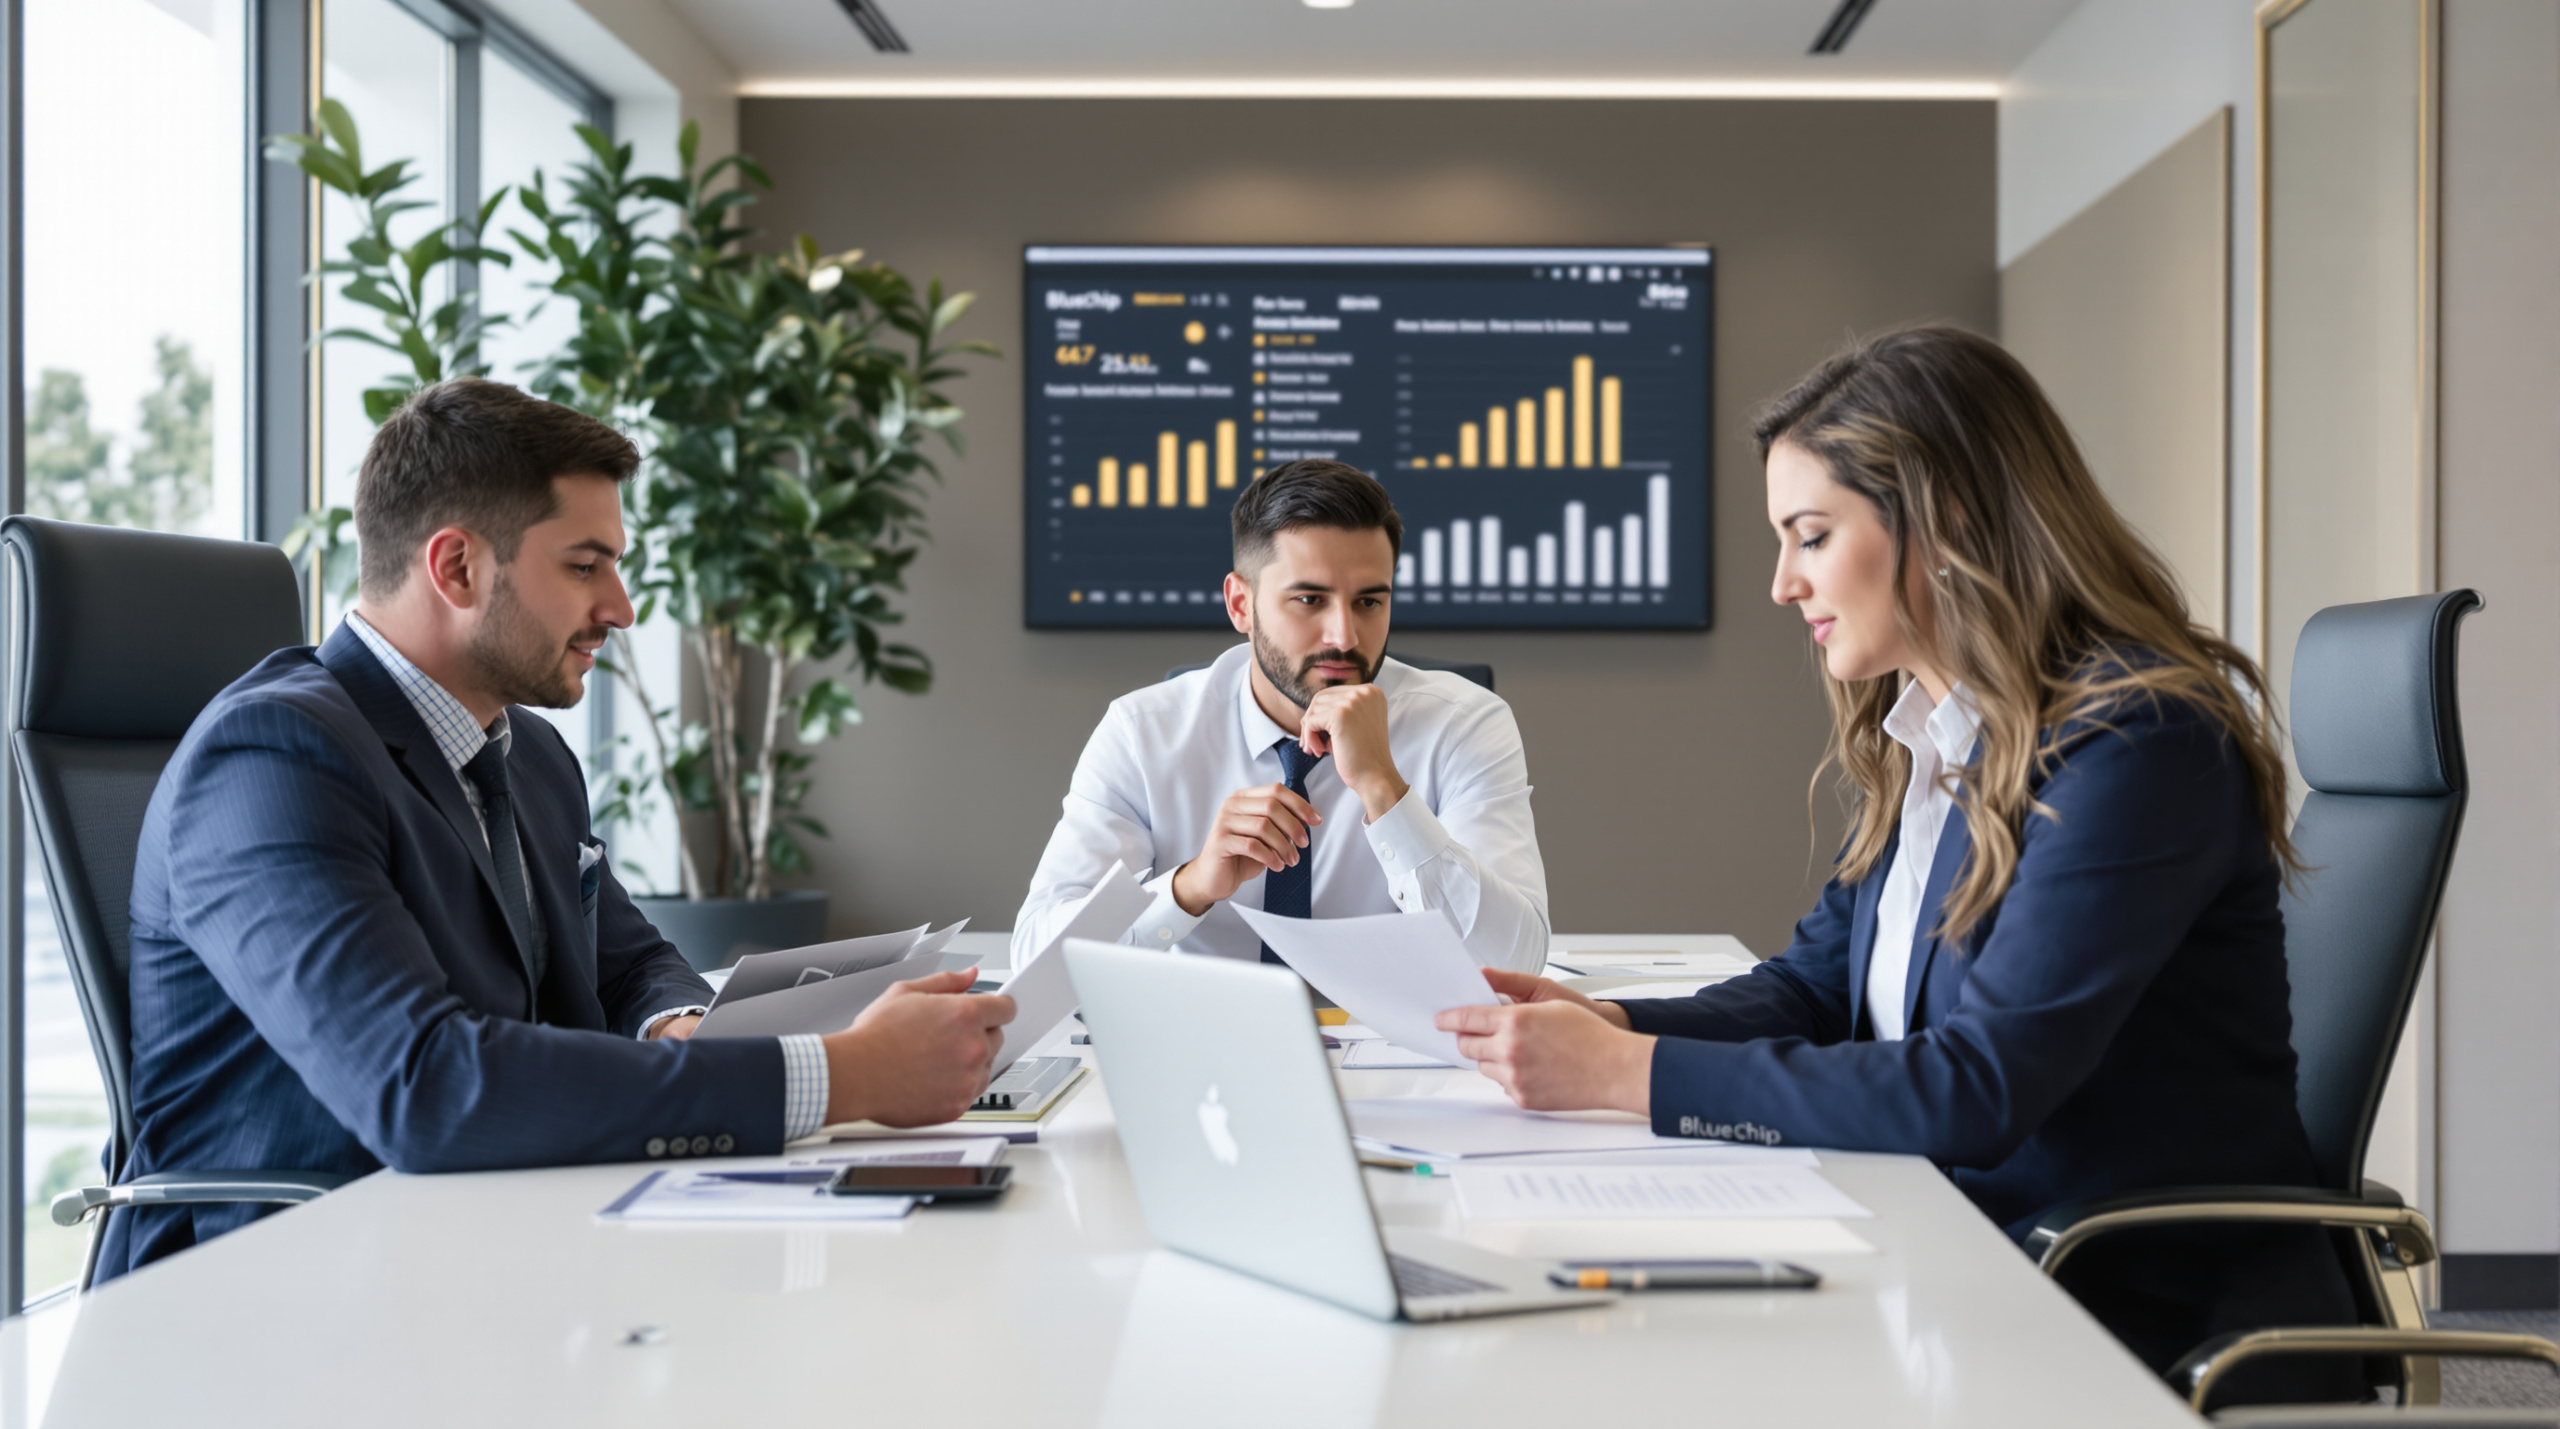
Leveraging technology to visualise risk metrics supports proactive decision-making. Dashboards that consolidate accounts receivable data and highlight overdue invoices, segmented by risk level, enable finance teams to focus resources efficiently. Features such as alerts on payment anomalies or concentration of overdue balances help maintain a live risk picture.
Integrations with accounting and ERP systems provide seamless updates, reducing manual reporting burdens. This real-time insight is vital to avoid surprises and to prioritise accounts that pose the greatest threat to liquidity.
How to interpret payment behaviour patterns effectively
Beyond raw numbers, understanding the context of payment behaviours is crucial. For instance, a long-term client with a sudden late payment may require a different response than a new customer with persistent delays. Patterns such as partial payments, disputed amounts, or requests for extensions warrant further investigation.
Implementing a Triage System to Categorise Overdue Invoices
With risk visibility established, organising overdue invoices into actionable categories streamlines prioritisation efforts and optimises resource allocation.
Criteria for high, medium, and low-risk account segmentation
Segmenting accounts based on multiple factors enhances decision clarity:
- High risk: Large outstanding balances, significantly overdue invoices (e.g., over 60 days), customers with deteriorating payment history, or those operating in financially stressed sectors.
- Medium risk: Moderate overdue amounts, invoices just beyond terms (30–60 days), customers with occasional late payments but stable overall.
- Low risk: Small overdue sums, recent payment delays with strong prior compliance, or accounts under active dispute resolution.
This stratification assists in determining which accounts require immediate follow-up, monitoring, or a more relaxed approach.
Balancing invoice age, amount, and customer history in triage
Effective triage weighs these variables to avoid simplistic prioritisation by invoice age alone. For example, a high-value invoice only a few days overdue with a risky customer might take precedence over an older, low-value invoice from a reliable client.
Maintaining a dynamic triage process that integrates updated data ensures responsiveness to evolving circumstances.
Examples of prioritisation workflows tailored to Australian commercial contexts
Australian businesses may encounter sector-specific challenges—such as construction invoice retention or seasonal variations—that influence prioritisation. Custom workflows might include:
- Immediate review of invoices flagged by internal sales or credit teams.
- Scheduled calls within 7 days for high-risk accounts to assess payment intent.
- Escalation to commercial collections partners after defined thresholds (e.g., 60 days overdue without response).
Adapting workflows to your commercial environment enhances effectiveness and aligns with local business practices. For related guidance, see How External Debt Collection Agencies Support Your Business.
Governance Structures to Align Credit Risk Decisions with Compliance
A robust governance framework ensures credit risk actions comply with legal and regulatory standards, which is especially important given the ASIC enforcement focus on payment default escalation.
Roles and responsibilities in managing escalating credit risk
Clear delineation of responsibilities prevents gaps or duplications. Typically:
- Credit managers: assess risk, authorise credit limits, and decide initial collection steps.
- Finance managers: oversee cash flow implications and approve escalations.
- Compliance officers or legal advisors: review adherence to regulatory requirements before formal recovery action.
Defined roles support accountability and consistent decision-making.
Incorporating ASIC enforcement insights into policy updates
ASIC's recent enforcement action highlights the regulator’s scrutiny on prudent credit risk management and compliant debt recovery. Finance teams should review policies to ensure:
- Accurate risk assessment processes.
- Transparent and fair communication with debtors.
- Timely escalation balanced with regulatory requirements.
Failing to heed enforcement signals risks not only financial loss but also regulatory penalties.
Ensuring compliant decision-making without compromising recovery potential
Maintaining compliance need not hinder recovery efforts. Policies should embed legal safeguards such as privacy considerations, dispute resolution protocols, and prohibition of aggressive collection tactics. Training staff on these aspects reduces risk and fosters professional interactions with debtors.
Embedding Cash Flow Support Mechanisms within Account Prioritisation
While prioritising risk, finance managers must also consider the broader business imperative of sustaining cash flow and customer relationships.
Aligning collection priorities with overall business cash flow needs
Not all overdue invoices have equal impact on business liquidity. Prioritisation should account for the debtor’s payment capacity relative to the business’s current cash flow demands. For example, prioritising key customers or those linked to ongoing contracts may secure future revenue streams.
Strategies to support customers while mitigating default risk
Offering flexible payment arrangements or staged repayments can preserve relationships and reduce default risk. Identifying customers genuinely struggling but willing to engage helps differentiate between willful non-payment and temporary hardship.
Regularly communicating options and expectations supports transparency and collaboration.
When to consider flexible payment arrangements versus escalation
Flexible approaches suit early-stage overdue accounts or clients with a strong history. However, beyond certain thresholds—such as repeated broken promises or prolonged non-payment—escalation to formal debt recovery may be necessary.
Decisions should be documented and aligned with governance policies to ensure consistency.
Practical Steps to Integrate Bluechip Collections into Your Escalation Workflow
Engaging a commercial debt collection agency like Bluechip Collections can complement internal efforts at the appropriate stage, particularly when payment default risk escalates beyond manageable levels. For related guidance, see Essential Qualities to Look for in a Brisbane Debt Collection Agency.
Identifying triggers for engaging external commercial debt collection
Triggers may include:
- Accounts overdue beyond internal credit control capacity.
- Customers unresponsive to repeated contact attempts.
- Complex or disputed accounts requiring specialist handling.
Recognising these signs early enables timely referral.
Overview of Bluechip’s technology-enabled debt recovery solutions
Bluechip provides tailored debt recovery services combining Australian market expertise with technology-enabled tools. Their solutions support pre-debt recovery engagement, compliant communication, and strategic escalation, enhancing efficiency without compromising regulatory adherence.
Maintaining compliance and customer relationship standards during outsourcing
Outsourcing should not mean relinquishing control. Collaborative partnership with Bluechip involves agreed parameters for recovery approach, compliance safeguards, and reporting. This preserves professional standards and supports the business’s reputation.
Case Scenario: Applying Enforcement Signals from ASIC to Refine Account Prioritisation
Summary of relevant ASIC enforcement action and its commercial implications
ASIC has signalled heightened regulatory attention on businesses’ handling of escalating payment defaults, emphasising transparent risk management and adherence to debt recovery laws. Non-compliance can result in enforcement penalties and reputational damage.
Adjusting internal credit risk policies in response to enforcement signals
Finance teams should:
- Review overdue account triage criteria to ensure early intervention.
- Reinforce governance controls on escalation authorisation.
- Enhance training on compliant collection practices.
These actions strengthen risk controls aligned with regulator expectations.
Lessons learnt: practical adjustments for finance teams
The enforcement signal underscores the need for structured risk visibility, disciplined triage, and compliance integration—combining to form a resilient credit management approach. It also highlights the value of partnering with experienced commercial collections providers for specialised support.
Building a Roadmap for Continuous Improvement in Credit Management Operations
Sustaining effective credit risk management requires ongoing evaluation and refinement.
Setting milestones for review and escalation process enhancements
Establish periodic reviews of triage accuracy, recovery outcomes, and compliance adherence. Adjust thresholds and workflows based on empirical data and evolving market conditions.
Leveraging data insights to refine risk prioritisation over time
Analysing collection success rates, customer payment trends, and enforcement outcomes informs smarter prioritisation. Data-driven insights help anticipate risks earlier and tailor responses.
Preparing finance teams for evolving regulatory and market challenges
Finance professionals should keep abreast of regulatory developments, such as ASIC guidance, and market shifts impacting debtor behaviour. Continuous training and process updates enhance readiness.
—
Contact Bluechip Collections to discuss commercial debt collection and accounts receivable support. For related guidance, see How a Debt Collection Agency Can Help With Aged Debts.